Buy beestar.eu ?
We are moving the project
beestar.eu .
Are you interested in purchasing the domain
beestar.eu ?
domain@kv-gmbh.de · 0541-91531010
Buy beestar.eu ?
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **
Similar search terms for Mortgage
Top-Angebote
Products related to Mortgage:
-
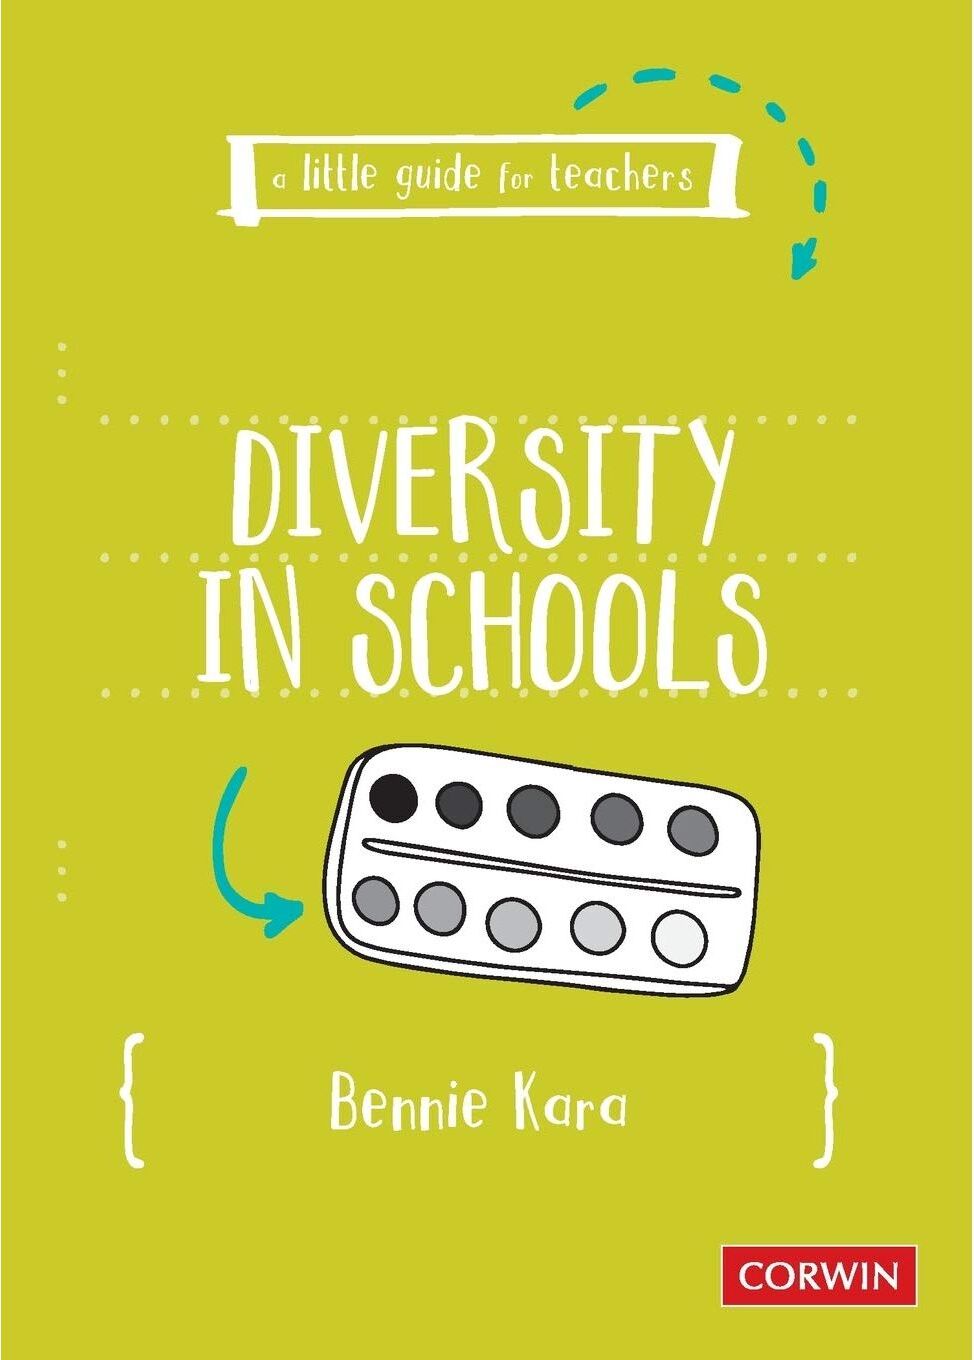
SAGE Publications A Little Guide for Teachers: Diversity in Schools (A Little Guide for Teachers)A Little Guide for Teachers: Diversity in Schools aims to provide starting points for teachers and leaders in creating a curriculum, either across disciplines or within subjects, that is as deep and diverse as their students. The Little Guide for Teachers series is little in size but BIG on all the support and inspiration you need to navigate your day to day life as a teacher. · Authored by experts in the field · Easy to dip in-and-out of · Interactive activities encourage you to write into the book and make it your own · Fun engaging illustrations throughout · Read in an afternoon or take as long as you like with it!12,99 £*Shipping: 2,99 £Secure redirect to the provider
-
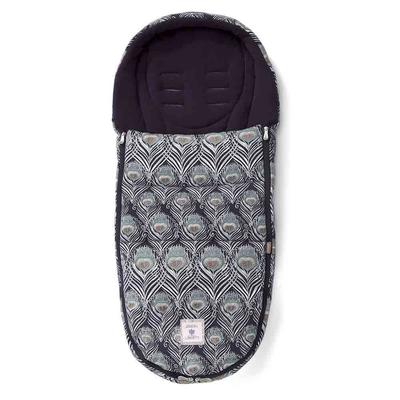
Mamas & Papas Special Edition Liberty Collaboration Cold Weather Plus FootmuffThe Cold Weather Plus Footmuff by Mamas & Papas is the ultimate footmuff for cold weather protection, and features an extra-soft fleece lining. Ideal for keeping baby warm and cozy when out and about in cool weather, you can even zip down to a liner...150,00 $*Shipping: 0,00 $Secure redirect to the provider
-
Yealink MeetingBoard 65-inch 4K Interactive Collaboration Display (MB65-A001)Yealink MeetingBoard 65 (MB65-A001): a 65-inch 4K Ultra HD LED-backlit interactive touch display for meeting rooms, with built-in camera, microphone array and speakers for Microsoft Teams Rooms and Zoom Rooms. Runs Android with a built-in processor and Wi-Fi.3896,99 £*Shipping: 0,00 £Secure redirect to the provider


-
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **
-
What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
-
How can I tell if a mortgage still exists?
To determine if a mortgage still exists on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for the deed of trust or mortgage document that was originally recorded when the loan was taken out. You can also contact the lender directly to inquire about the status of the mortgage and any outstanding balance. Additionally, you can request a copy of your credit report, which should list any current mortgages or liens on your property. **

How was the house purchased without a mortgage deed?
The house was purchased without a mortgage deed through a cash transaction. This means that the buyer paid for the house in full with their own funds, rather than taking out a mortgage loan from a bank or other financial institution. This type of transaction is common in situations where the buyer has enough savings or access to funds to purchase the property outright, without the need for a mortgage. **
What is the difference between a mortgage and a loan?
A mortgage is a specific type of loan that is used to purchase real estate, typically a home. It is a secured loan, meaning the property serves as collateral for the loan. On the other hand, a loan is a broader term that can refer to various types of borrowing, such as personal loans, auto loans, or student loans. Loans can be secured or unsecured, depending on the lender's requirements. **
Top-Angebote
Products related to Mortgage:
-
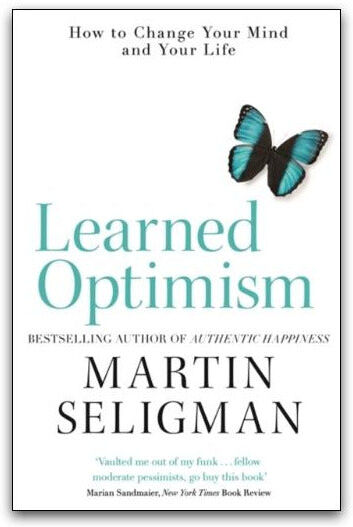
Nicholas Brealey Publishing Learned Optimism by Martin E. P. Seligman Positive Psychology, Resilience & Personal GrowthDiscover the life-changing power of positive thinking with Learned Optimism by renowned psychologist and positive psychology pioneer Martin E. P. Seligman. In this influential book, Seligman explains how optimism is not simply an inborn trait—it can be learned. Drawing on decades of psychological research, he introduces practical techniques to help readers recognize negative thought patterns, develop a more constructive outlook, and build resilience in the face of life's challenges. Whether you're looking to improve your mental wellbeing, boost confidence, manage setbacks, or achieve personal and professional success, Learned Optimism provides evidence-based strategies that can help you cultivate a healthier, more positive mindset. Why Readers Love This Book: Written by the founder of positive psychology Research-based techniques for building optimism and resilience Practical exercises to overcome negative thinking Helps improve confidence, wellbeing, and emotional strength Ideal for readers interested in psychology, self-improvement, and mental wellness A modern classic in psychology, Learned Optimism offers practical tools to help you develop a more resilient mindset and lead a happier, more fulfilling life.5,99 £*Shipping: 2,99 £Secure redirect to the provider
-
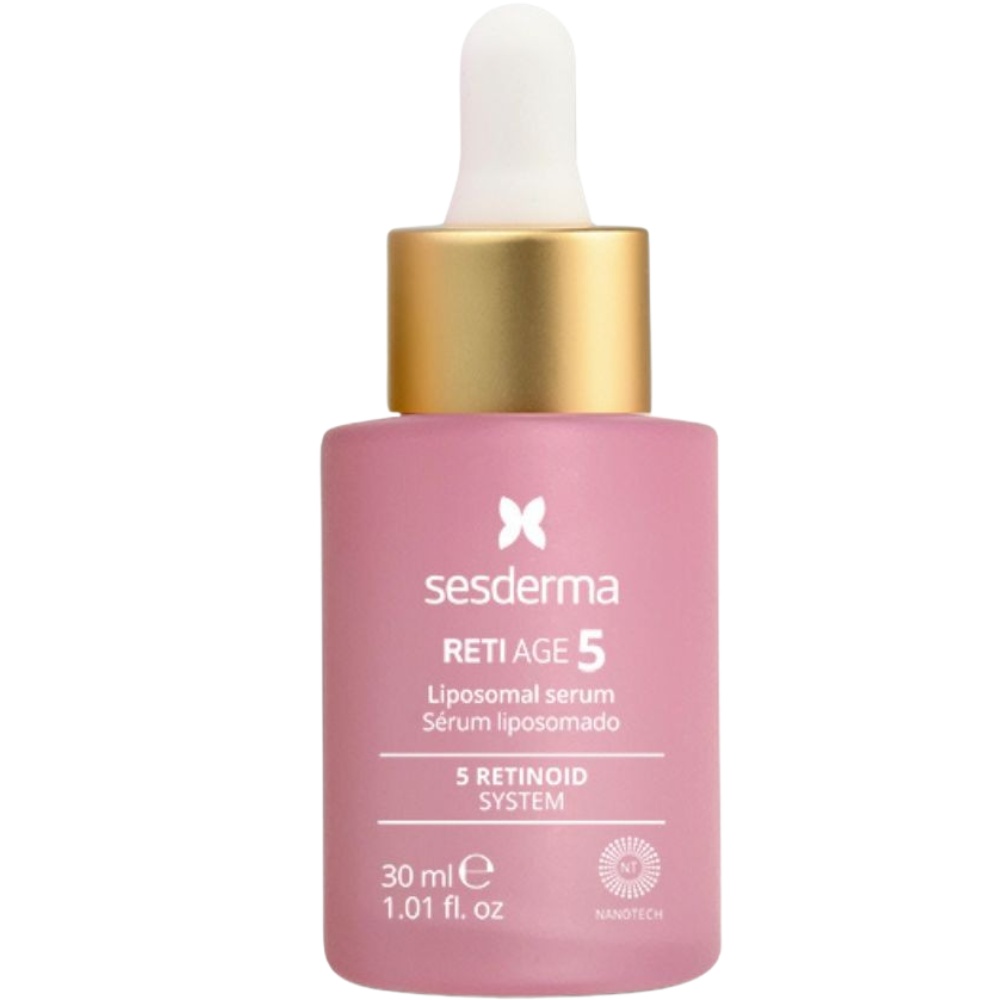
Sesderma Reti Age 5 Liposomal Serum Anti-Aging Innovation 30mLA facial serum for wrinkles and signs of ageing. Reduces wrinkles and fine lines. Hydrates and strengthens barrier. Restores youthful radiance. 5-Retinoid System: smooths wrinkles, accelerates renewal, and boosts collagen. Biomimetic Peptides: fill expression lines by stimulating collagen synthesis.54,51 £*Shipping: 5,34 £Secure redirect to the provider
-
SAGE Publications A Little Guide for Teachers: Diversity in Schools (A Little Guide for Teachers)A Little Guide for Teachers: Diversity in Schools aims to provide starting points for teachers and leaders in creating a curriculum, either across disciplines or within subjects, that is as deep and diverse as their students. The Little Guide for Teachers series is little in size but BIG on all the support and inspiration you need to navigate your day to day life as a teacher. · Authored by experts in the field · Easy to dip in-and-out of · Interactive activities encourage you to write into the book and make it your own · Fun engaging illustrations throughout · Read in an afternoon or take as long as you like with it!12,99 £*Shipping: 2,99 £Secure redirect to the provider
-
What is a primary mortgage financing?
A primary mortgage financing refers to the initial loan that a borrower obtains from a lender to purchase a home or property. This type of financing is typically used to cover the majority of the purchase price of the property, and is secured by the property itself. The borrower makes regular payments to the lender over a set period of time, usually 15 or 30 years, until the loan is fully repaid. Primary mortgage financing is a common way for individuals to become homeowners without having to pay the full purchase price upfront. **
-
How does the mortgage work in Monopoly?
In Monopoly, players can purchase properties when they land on them. If a player lands on an unowned property and chooses not to buy it, the property goes up for auction. If a player cannot afford to purchase a property, they have the option to mortgage their own properties to raise funds. When a property is mortgaged, the owner receives cash equal to half of the property's value, but they must pay 10% interest when they unmortgage the property. **
-
Where can I get a mortgage deed?
You can obtain a mortgage deed from a mortgage lender or financial institution that is providing you with the loan for purchasing a property. The mortgage deed is a legal document that outlines the terms and conditions of the mortgage agreement between the borrower and the lender. It is typically prepared by the lender's legal team and signed by both parties before the loan is disbursed. **
-
Can the mortgage on the house increase?
Yes, the mortgage on a house can increase under certain circumstances. For example, if the homeowner has an adjustable-rate mortgage, the interest rate can increase over time, causing the monthly mortgage payment to go up. Additionally, if the homeowner has a mortgage with an escrow account for property taxes and homeowners insurance, an increase in these expenses can also lead to an increase in the monthly mortgage payment. Finally, if the homeowner takes out a home equity loan or line of credit, this can also increase the overall debt secured by the house. **
Similar search terms for Mortgage
-
Mamas & Papas Special Edition Liberty Collaboration Cold Weather Plus FootmuffThe Cold Weather Plus Footmuff by Mamas & Papas is the ultimate footmuff for cold weather protection, and features an extra-soft fleece lining. Ideal for keeping baby warm and cozy when out and about in cool weather, you can even zip down to a liner...150,00 $*Shipping: 0,00 $Secure redirect to the provider
-
Yealink MeetingBoard 65-inch 4K Interactive Collaboration Display (MB65-A001)Yealink MeetingBoard 65 (MB65-A001): a 65-inch 4K Ultra HD LED-backlit interactive touch display for meeting rooms, with built-in camera, microphone array and speakers for Microsoft Teams Rooms and Zoom Rooms. Runs Android with a built-in processor and Wi-Fi.3896,99 £*Shipping: 0,00 £Secure redirect to the provider
-
Dell Pro Silent Wired Collaboration Keyboard KB525C UK QWERTY - BlackProfessional wired collaboration keyboard featuring spill-resistant design and silent key switches. Includes 15 programmable shortcut keys, dedicated Copilot key, and volume controls for enhanced productivity. Full numeric keypad and UK QWERTY layout with comprehensive 3-year NBD Advance Exchange support.45,99 £*Shipping: 0,00 £Secure redirect to the provider
-
HARPERCOLLINS Creative Confidence by Tom & David Kelley – Unleashing Your Creative Potential & Innovation MindsetA powerful and inspiring book from the founders of IDEO, the award-winning design firm, on unleashing the creativity that lies within each and every one of us. Too often, companies and individuals assume that creativity and innovation are the domain of the ‘creative types’. But two of the foremost experts in innovation, design and creativity on the planet show us that each and every one of us is creative. In an entertaining and inspiring narrative that draws on countless stories from their work at IDEO, and with many of the world's top companies and design firms, David and Tom Kelley identify the principles and strategies that will allow us to tap into our creative potential in our work lives, and in our personal lives, allow us to think outside the box in terms of how we approach and solve problems. ‘Creative Confidence’ is a book that will help each of us be more productive and successful in our lives and in our careers.4,95 £*Shipping: 1,99 £Secure redirect to the provider
-
What do I need to cancel a mortgage?
To cancel a mortgage, you typically need to pay off the remaining balance of the loan. This can be done by making a lump sum payment for the full amount owed. Once the loan is paid off, the lender will provide you with a satisfaction of mortgage document, which officially cancels the mortgage lien on the property. It's important to follow the specific procedures outlined by your lender to ensure the mortgage is properly canceled. **
-
How can I tell if a mortgage still exists?
To determine if a mortgage still exists on a property, you can start by checking the public records at the county recorder's office where the property is located. Look for the deed of trust or mortgage document that was originally recorded when the loan was taken out. You can also contact the lender directly to inquire about the status of the mortgage and any outstanding balance. Additionally, you can request a copy of your credit report, which should list any current mortgages or liens on your property. **
-
How was the house purchased without a mortgage deed?
The house was purchased without a mortgage deed through a cash transaction. This means that the buyer paid for the house in full with their own funds, rather than taking out a mortgage loan from a bank or other financial institution. This type of transaction is common in situations where the buyer has enough savings or access to funds to purchase the property outright, without the need for a mortgage. **
-
What is the difference between a mortgage and a loan?
A mortgage is a specific type of loan that is used to purchase real estate, typically a home. It is a secured loan, meaning the property serves as collateral for the loan. On the other hand, a loan is a broader term that can refer to various types of borrowing, such as personal loans, auto loans, or student loans. Loans can be secured or unsecured, depending on the lender's requirements. **
* All prices are inclusive of VAT and, if applicable, plus shipping costs. The offer information is based on the details provided by the respective shop and is updated through automated processes. Real-time updates do not occur, so deviations can occur in individual cases. ** Note: Parts of this content were created by AI.